Cashli: Cash Advance & Rewards

Screenshots
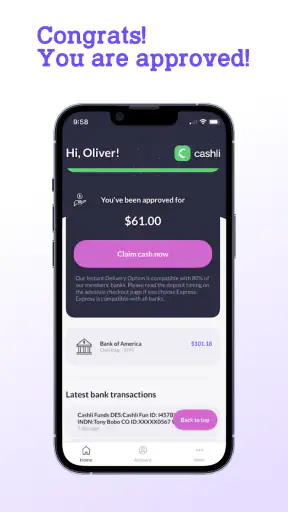
Details
- Rating
- 2.78K reviews
- Version
- 1.0.19
- Developer
- Cashli Funds
Analysis by Norviv
Cashli: Cash Advance & Rewards is a finance app built around a simple promise: helping users handle a short-term cash squeeze while offering a rewards angle alongside it. I approached it as the kind of tool someone might open when an unexpected expense arrives before payday, not as a replacement for a bank account or a long-term budgeting system. That distinction matters, because the app’s usefulness depends heavily on how carefully you treat a cash advance.
My overall impression is that Cashli is easy to understand at a glance, but it deserves a more cautious reading than its brief store message suggests. The app is free to install, aimed at an Everyone audience, and developed by Cashli Funds. It sits in the finance category, where convenience is valuable but clarity is even more important. If you are considering it, I would focus less on the idea of getting money quickly and more on the complete cost, repayment expectations, eligibility steps, and how the service fits into your existing finances.
How Cashli feels in its current form
The current release is version 1.0.19, and that gives the app a relatively early-stage feel rather than the impression of a decades-old financial institution. It has reached more than one hundred thousand installs, with an average rating of 4.1 from roughly five thousand ratings and about three thousand written reviews. Those figures suggest that many people are willing to try it, while the rating also tells me not to treat the experience as universally smooth.
In practical terms, Cashli is best viewed as a short-term financial tool. It may appeal to someone dealing with a modest timing problem, such as a utility bill arriving a few days before their salary. It is less suitable for recurring shortfalls, large purchases, or anyone who is already using one loan to cover another. A cash advance can solve a calendar problem, but it cannot repair a monthly budget that is consistently running behind.
The rewards element gives the app a slightly different identity from a plain advance service. Still, I would not let the word “rewards” distract from the central decision. Any benefit attached to an app like this should be treated as secondary until you understand how the advance works, what you must repay, and whether the arrangement is genuinely affordable for you.
The first-use decision is more important than the download
Because the app is free, installing it is not the same as committing to an advance. That makes it reasonable to explore the opening screens and read the terms before deciding whether to continue. I recommend taking screenshots or notes of the key figures shown during the application process, especially the amount you could receive, the amount expected back, the repayment timing, and any optional services.
This is one of the most useful habits with Cashli: separate the available amount from the amount you actually need. A larger offer is not automatically a better offer. If your problem is a small grocery gap, accepting more than necessary can create a larger repayment obligation without solving anything extra. I would request only the smallest amount that handles the specific bill.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Another practical step is to check whether the repayment date lines up with your real income date rather than an optimistic estimate. A salary can arrive later because of a weekend, a holiday, or an employer’s processing schedule. If the app presents a date that feels tight, I would pause instead of assuming I could adjust it later.
What the version and release history suggest
Cashli was released on July 18, 2023, and the current version number shows that the product has moved beyond its initial launch build. That is a useful sign of ongoing maintenance, but it is not proof that every part of the experience is mature. A version update can improve stability, refine screens, or change how an application presents information; it does not automatically tell me whether the underlying financial terms are right for a particular user.
For existing users, the move to version 1.0.19 is most relevant as a reminder to review the app after updating. I would check whether the application still displays the same repayment details in the same place, whether notifications are understandable, and whether the account flow remains familiar. Financial apps should not be judged only by appearance, so I would also reread the current terms before accepting a new advance rather than relying on memory from an earlier use.
The minimum operating-system requirement is Android 8.0, which keeps Cashli accessible to people using older Android phones. That is convenient, particularly if you do not upgrade devices often. At the same time, older phones can have outdated security settings or limited storage, so I would make sure the device itself is protected with a screen lock and current system updates where available. The app’s compatibility does not remove the need for sensible phone security.
How I would use it in an everyday situation
Imagine that your electricity payment is due on a Tuesday and your paycheck arrives on Friday. In that situation, I would first check whether the provider offers a short extension, whether a bill can be moved, or whether I can use existing savings without creating another obligation. Only after those options would I consider Cashli. If I did proceed, I would enter the smallest necessary amount, record the repayment date in my calendar, and leave enough money untouched for essential expenses.
That workflow is deliberately conservative. The app may make access feel simple, but the repayment still affects the rest of the week. I would not use a cash advance for discretionary shopping, a subscription renewal, or an impulse purchase. Those expenses can usually wait, while the repayment cannot be treated as imaginary future money.
A second useful scenario is an irregular expense, such as a necessary household replacement. Here, the decision depends on whether the item is truly urgent and whether the next pay cycle can absorb the repayment comfortably. Cashli may be more practical than a lengthy traditional loan application for a small, time-sensitive need, but a bank overdraft, an employer advance, or help from a trusted person could be better if those alternatives have clearer or lower costs.
Where it differs from ordinary finance alternatives
Compared with a traditional bank loan, Cashli is positioned around speed and a smaller, more immediate need rather than a structured borrowing relationship. That can reduce friction for someone who does not want a lengthy application. The trade-off is that short-term products require sharper attention to timing. A bank loan may feel slower, but its documentation and repayment structure can be easier to evaluate over a longer period.
Compared with a credit card, Cashli may be attractive to someone who does not want to open another revolving credit line. However, a credit card can offer more flexibility for purchases, while a cash advance can impose a tighter repayment window. Neither option is automatically cheaper. I would compare the total repayment, not just the amount placed in your account.
Compared with a budgeting app, Cashli serves a completely different purpose. A budgeting tool helps you see patterns before a crisis arrives; Cashli is something you might consider after a timing problem has already appeared. If you find yourself returning to it because the same bills are difficult every month, a spending review or a free debt-advice service is likely to help more than another advance.
Small details that deserve careful attention
One non-obvious trade-off is the difference between convenience and financial visibility. A fast application can make a decision feel smaller than it really is. I would slow the process down by writing the repayment amount next to my upcoming expenses. If the numbers leave no room for food, transport, housing, or other essentials, the advance is not affordable simply because the app offers it.
A second is the way rewards can influence behavior. Rewards may make an ordinary financial action feel like progress, but they should never justify borrowing. I would evaluate the rewards only after confirming that the advance itself makes sense. If earning a benefit encourages you to open the app more often or take money you would otherwise avoid borrowing, the reward has become a cost in practice.
A third is record-keeping. I would save the confirmation screen and repayment information in a private note, then set two reminders: one several days before the due date and another on the date itself. This is especially helpful if you have several financial apps, changing income dates, or automatic payments that compete for the same balance. The reminder system is not a Cashli feature; it is a simple safeguard that makes using a short-term service less error-prone.
I would also read every screen rather than tapping through quickly. Look for whether the displayed amount is the amount received or the amount repaid, and distinguish any optional choice from a required step. If the wording is unclear, that is a reason to stop and seek clarification, not a reason to guess. With financial products, a confusing sentence can matter more than a polished interface.
Who is likely to benefit, and who should skip it
Cashli may suit an adult who has a one-off, modest cash-flow gap, understands the repayment schedule, and can cover the obligation from confirmed income. It may also suit someone who wants to investigate a short-term option without paying to download the app. The free price removes one barrier to trying the service, although it does not tell you what borrowing may cost.
I would advise skipping it if your income is unpredictable, your essential bills already exceed your available money, or you are looking for a solution to several months of debt. I would also avoid it if you are uncomfortable sharing financial information with an app or if you cannot clearly explain when and how repayment will happen. In those cases, a bank adviser, credit counselor, employer payroll option, or trusted support network may be a safer direction.
The Everyone content rating describes the app’s broad store audience, but it should not be confused with a recommendation for every age or financial situation. Borrowing decisions require adult judgment, and a young or financially inexperienced user should involve a responsible adult before accepting any obligation. The rating describes content suitability, not affordability.
Questions I would answer before accepting an advance
The first question is whether the app can guarantee that I will receive money. I would not assume that an advertised possibility equals approval. Eligibility and the final offer should be judged from the actual application screens, and I would avoid planning a bill payment around money that has not arrived.
The second is whether using Cashli affects my broader financial position. Even a single repayment can compete with rent, groceries, transport, or existing automatic payments. I would place the expected repayment into my budget before accepting anything, not after the money is already available.
The third is whether the service is better than an alternative I already have. If my bank offers a clearly explained overdraft, if a bill provider allows a free payment change, or if I can use emergency savings without penalty, those choices may be preferable. Cashli is most interesting when it fills a genuine short-term gap and the alternatives are less suitable—not simply because it is easy to open.
The fourth is what happens if circumstances change. Before proceeding, I would look for the app’s instructions about repayment problems and support. I would not wait until the due date to discover how to ask for help. A service can be useful while still requiring users to understand its process for missed or delayed payments.
What I would like to see users watch over time
As Cashli continues beyond version 1.0.19, I would watch for clearer explanations of total repayment, stronger in-app budgeting context, and a smoother way to review past advances and rewards together. Those improvements would help users understand not only what they can receive, but also how each decision affects the next pay cycle.
I would also pay attention to whether updates make the experience more transparent for returning users. A good finance app should make important terms easy to find after the first application, not only during sign-up. Clear history, prominent due dates, and straightforward support pathways would matter more to me than decorative changes.
The current rating and adoption suggest that Cashli has found an audience, but popularity should not replace personal checking. I would keep notifications enabled only if they are useful, review the app after updates, and remove access if I no longer need the service. Those are simple steps, yet they prevent a temporary financial tool from becoming a background habit.
My final view is cautiously positive. Cashli can be worth exploring for a specific, short-lived cash-flow problem, especially if you compare its actual repayment terms with the alternatives available to you. I would not recommend treating it as spare income, and I would not use the rewards angle as a reason to borrow. The best use of Cashli is a carefully measured bridge, not a permanent financial plan.
For the right user, the free app and accessible Android requirement make the first look convenient. For anyone facing repeated shortages, unclear repayment capacity, or larger debt concerns, a budgeting change or personal financial guidance is the better next step. That balance is what makes this finance app useful: not the promise of quick money by itself, but the possibility of handling one clearly defined gap without pretending the underlying budget problem has disappeared.
Frequently Asked Questions
01What is Cashli: Cash Advance & Rewards, and how does it work?
Cashli: Cash Advance & Rewards is a financial app that may help eligible users access cash advances and earn rewards through selected activities or offers. After creating an account, you may be asked to provide personal and financial information so the service can assess eligibility. Available features, advance amounts, repayment terms, fees, and reward opportunities can vary depending on your location and account details.
02Is Cashli a loan, and what fees or repayment terms should I expect?
A cash advance is not free money and should be treated as a short-term financial obligation. Before accepting an offer through Cashli, carefully review the total repayment amount, any subscription or service charges, optional tips, transfer fees, due date, and consequences of late repayment. The actual cost and terms may differ by user, state, or country, so read every disclosure shown in the app.
03Who can use Cashli, and what information is required to apply?
Eligibility requirements may include being at least 18 years old, living in a supported region, having a valid government-issued identity document, maintaining an eligible bank account, and demonstrating a qualifying source of income or transaction history. Cashli may request access to identity, contact, banking, and device information for verification. Approval is not guaranteed, and submitting an application may involve a review of your financial details.
04How do Cashli rewards work, and can they be converted into cash?
Rewards generally depend on completing qualifying actions, using participating offers, or meeting conditions displayed inside the app. Not every activity will provide an immediate payout, and some rewards may require verification, a minimum balance, or a waiting period. Check the current rewards rules before participating, including expiration dates, withdrawal limits, eligible redemption methods, and whether rewards are promotional rather than guaranteed income.
05Is Cashli safe to download, and what should I check before using it?
Download Cashli only from the official Google Play Store or Apple App Store, and confirm that the developer, privacy policy, and user reviews match the legitimate application. Because the app may handle sensitive financial information, review its requested permissions and data-sharing practices before registering. Never provide banking passwords, verification codes, or payment details through unofficial links, messages, or websites claiming to represent Cashli.


